Shares of Blue Ridge Bankshares, Inc. BRBS have gained 0.6% since the company reported its earnings for the quarter ended June 30, 2026. This compares to the S&P 500 Index’s 1.5% rise over the same time frame. Over the past month, the stock lost 0.6% compared with the S&P 500’s 0.9% loss.
Blue Ridge Bankshares’ Earnings Snapshot
Blue Ridge Bankshares reported a net loss of $0.2 million, or breakeven per diluted common share, for the second quarter of 2026, against net income of $1.3 million, or $0.01 per diluted common share, in the year-ago quarter. Net interest income declined 16.6% year over year to $16.5 million from $19.8 million, while total interest income fell 16.9% to $28.8 million.
Noninterest income decreased 45.4% to $1.8 million, primarily reflecting lower other income and the absence of mortgage banking-related revenues. Total noninterest expense declined 27.8% year over year to $15.9 million, led by lower personnel, FDIC insurance and technology costs.
BRBS does not report results by operating segment.
BRBS’ Other Key Business Metrics
Loans held for investment (LHFI) increased $19.6 million to $1.85 billion from $1.83 billion at the end of the first quarter, marking the first quarterly loan growth in 13 quarters and representing an annualized growth rate of 4%. Growth was primarily driven by commercial and residential mortgage lending. During the quarter, Blue Ridge Bankshares also began purchasing adjustable-rate residential mortgage loans originated by a third-party partner to expand its consumer mortgage offering.
Total assets declined to $2.33 billion from $2.41 billion at the end of the first quarter, largely reflecting lower cash balances after the special dividend payment and reduced brokered deposits. Total deposits fell sequentially to $1.86 billion from $1.89 billion as brokered deposits continued to run off, although the proportion of noninterest-bearing demand deposits improved to 21.3% from 20.7% in the prior quarter. Net interest margin edged up to 2.91% from 2.90%, while the cost of deposits declined to 2.25% from 2.27%, reflecting an improved funding mix.
Brokered deposits fell to $185.8 million from $296.1 million a year earlier, lowering their share of total deposits to 10% from 14.7%.
Credit quality weakened during the quarter. Nonperforming loans increased to $31.2 million, or 1.34% of total assets, from $21 million, or 0.87% of total assets, as of March 31, 2026, primarily due to an $11.4 million out-of-market lending relationship that was moved to nonaccrual status.
BRBS established a $1.5 million reserve against the exposure. The allowance for credit losses increased to 1.11% of LHFI from 1.05% in the prior quarter.
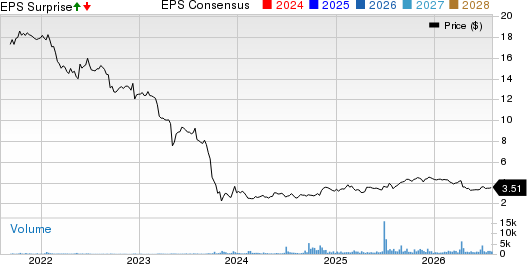
Blue Ridge Bankshares, Inc. Price, Consensus and EPS Surprise

Blue Ridge Bankshares, Inc. price-consensus-eps-surprise-chart | Blue Ridge Bankshares, Inc. Quote
Blue Ridge Bankshares’ Management Commentary
Interim president and chief executive officer Harry Golliday said that Blue Ridge Bankshares’ multiyear effort to de-risk the balance sheet and refocus on community banking customers has begun producing results. Golliday highlighted the return to loan growth, an improved deposit mix and ongoing expense reductions as drivers of stronger pre-tax, pre-provision earnings.
Management also stated that economic conditions across the bank’s markets remain supportive, with healthy business investment and consumer spending contributing to encouraging loan and deposit pipelines. Additionally, BRBS expects the benefits from recently implemented expense reduction initiatives to become more evident during the second half of 2026.
Factors Influencing BRBS’ Quarter
Second-quarter results were significantly affected by higher credit costs. BRBS recorded an after-tax provision for credit losses of $2.1 million against an after-tax recovery of $0.5 million in both the preceding quarter and the year-ago period. The provision reflected net charge-offs, higher reserves for the nonperforming out-of-market relationship and growth in the loan portfolio. An additional provision was recorded for unfunded commercial construction commitments.
Profitability also reflected lower severance expenses and continued cost reductions. Excluding severance costs, pre-tax, pre-provision income improved to $2.9 million from $1.4 million in the second quarter of 2025.
Noninterest expense benefited from lower salaries and employee benefits, reduced FDIC insurance premiums, lower technology spending and a decline in headcount to 269 employees from 333 a year earlier. Noninterest income, however, was reduced by a loss on the liquidation of an equity-method investment and lower mortgage-related income.
Blue Ridge Bankshares’ Guidance
Blue Ridge Bankshares did not provide formal financial guidance for the remainder of 2026. Management stated that favorable loan and deposit pipelines, together with the expected realization of recent expense reduction measures during the second half of the year, should support future operating performance.
BRBS’ Other Developments
During the quarter, the company continued restructuring its balance sheet by reducing brokered deposits and strengthening funding quality. Subsequent to June 30, 2026, Blue Ridge Bankshares redeemed the remaining balance of its 2029 subordinated notes, leaving the company with no outstanding subordinated debt.
BRBS declared and paid a special cash dividend of $0.60 per common share during the quarter, totaling approximately $54.1 million. During the quarter, the company also launched a partnership with a third-party residential mortgage originator to expand its consumer mortgage offerings. No acquisitions or divestitures were announced during the quarter.
Beyond Nvidia: AI’s Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren’t likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
Blue Ridge Bankshares, Inc. (BRBS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.